01 / THE VISION

Frozzo,
on the café menu.

A proposed route from an existing vegetarian snack range to repeat supply across UAE café outlets. Start with one café group and expand when the product and economics hold.

Explore the offer

Explore a proposed menu and commercial case.

FROM HALDWANITO UAE CAFÉS
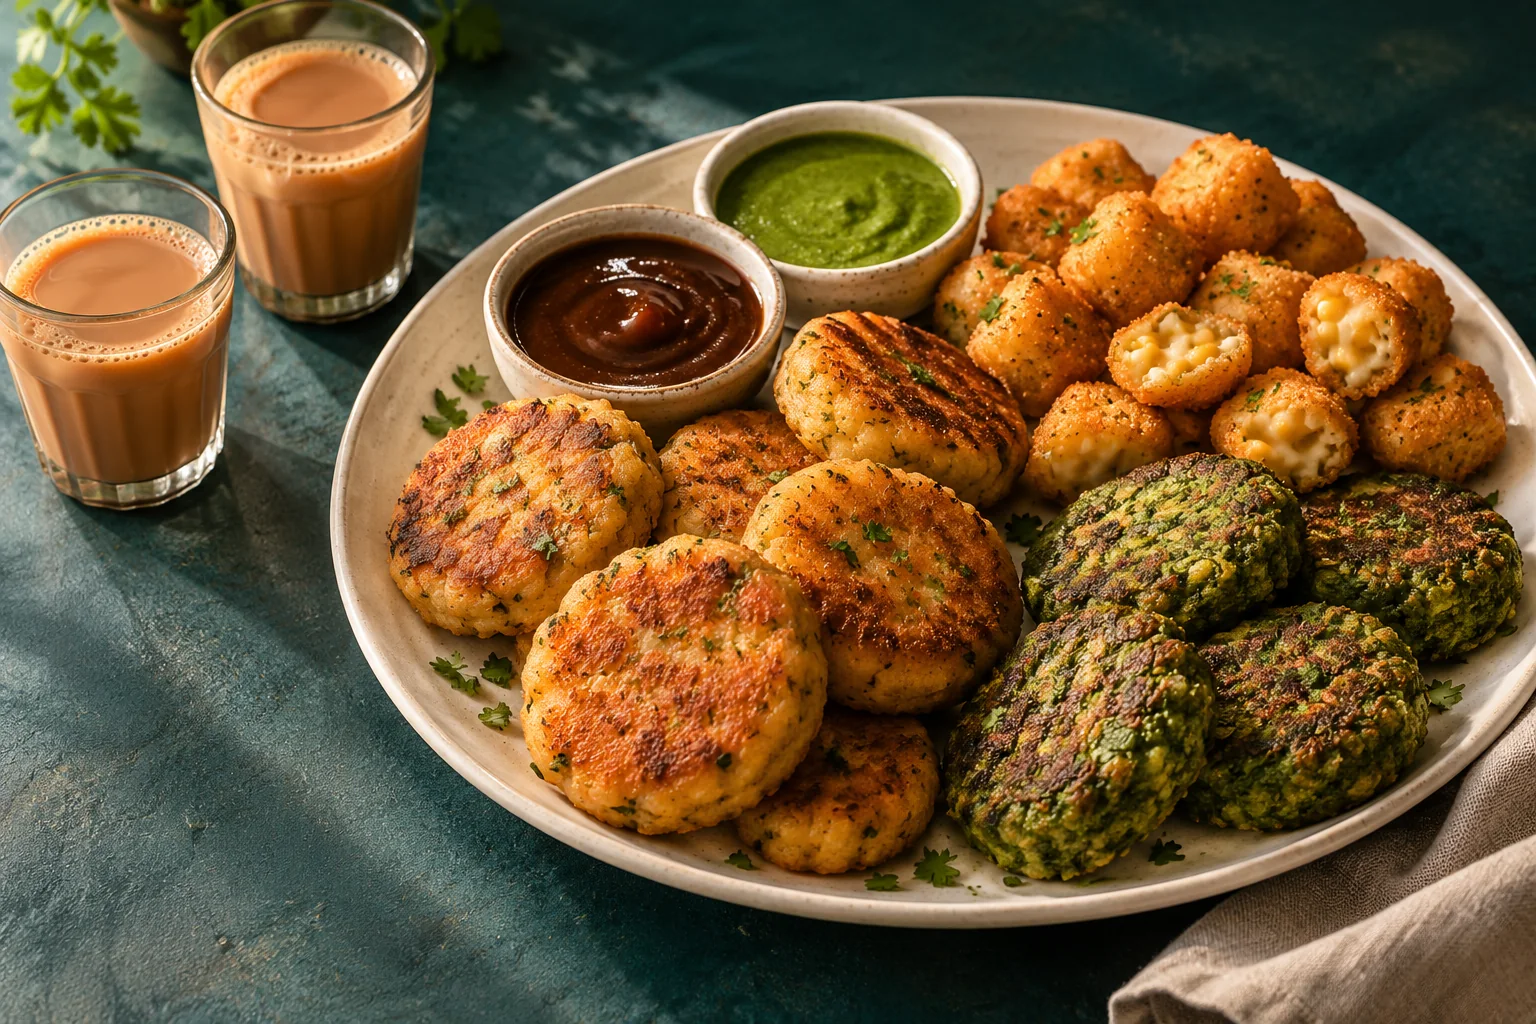
Serving illustration: aloo tikki, cheese corn nuggets and hara bhara kebab with two dips and chai
ON THE TABLEThe Frozzo
sharing plate
Three snacks. Mint & tamarind dips.
Proposed serving · AI-created illustration
AN OBSERVED CAFÉ OCCASION

UAE café menus already pair chai with Indian snacks. A focused Frozzo offer could compete through taste, preparation consistency and supply economics.

THE OPPORTUNITY

Test one café-group account, then build repeat supply if the product, demand and commercial terms justify it.
01 / 05The vision

REFERENCE NOTES

Products & market context

Product names and pack images come from Pal Frozen Foods. The menu combinations are proposed serving concepts. Confirm current UAE specifications and availability before any offer.

Checked 30 October 2026. Market examples do not imply a buyer relationship or supplier opening. Serving images are AI-created illustrations; actual product appearance and portions may differ. No prices or quantities here constitute a quote.

SCENARIO CALCULATION

From servings to supply.

Monthly kilograms
Outlets × daily servings × trading days × Frozzo grams per serving ÷ 1,000
Pal sales
Kilograms × Pal selling price per kg
Pal contribution
Sales less kilograms × variable cost per kg. Fixed overheads and tax are excluded.
Café contribution per serving
Menu price less Frozzo supply cost, accompaniments and all other variable serving costs.
Incremental operating profit
Pal contribution less additional monthly fixed operating costs for this account. Leave unestimated when those costs are unknown. Interest, tax and one-off trial setup are excluded.
Working-capital estimate
(Monthly variable cost ÷ 30 × stock days) + (monthly sales ÷ 30 × customer credit days). Supplier credit is excluded.
Recovering the initial trial cost
One-off trial cost ÷ positive contribution per kg. This is a volume threshold, not a promised payback period.

These calculations use a steady-state 30-day planning month. They do not model seasonality, delayed payments, bad debt, returns, ramp-up or spare manufacturing capacity. Replace illustrative inputs with approved commercial data.